The traditional fresh markets; don’t forget them!

By Cleo van Rijk

For my MSc thesis I researched the food chains of the traditional markets in the province of Noord-Brabant in the south of the Netherlands. Hardly any research has been done on the food chains of traditional markets in the Netherlands. Therefore I have researched the fresh markets of the four biggest cities in Noord-Brabant: ’s-Hertogenbosch, Breda, Tilburg en Eindhoven. This has led to very interesting results.
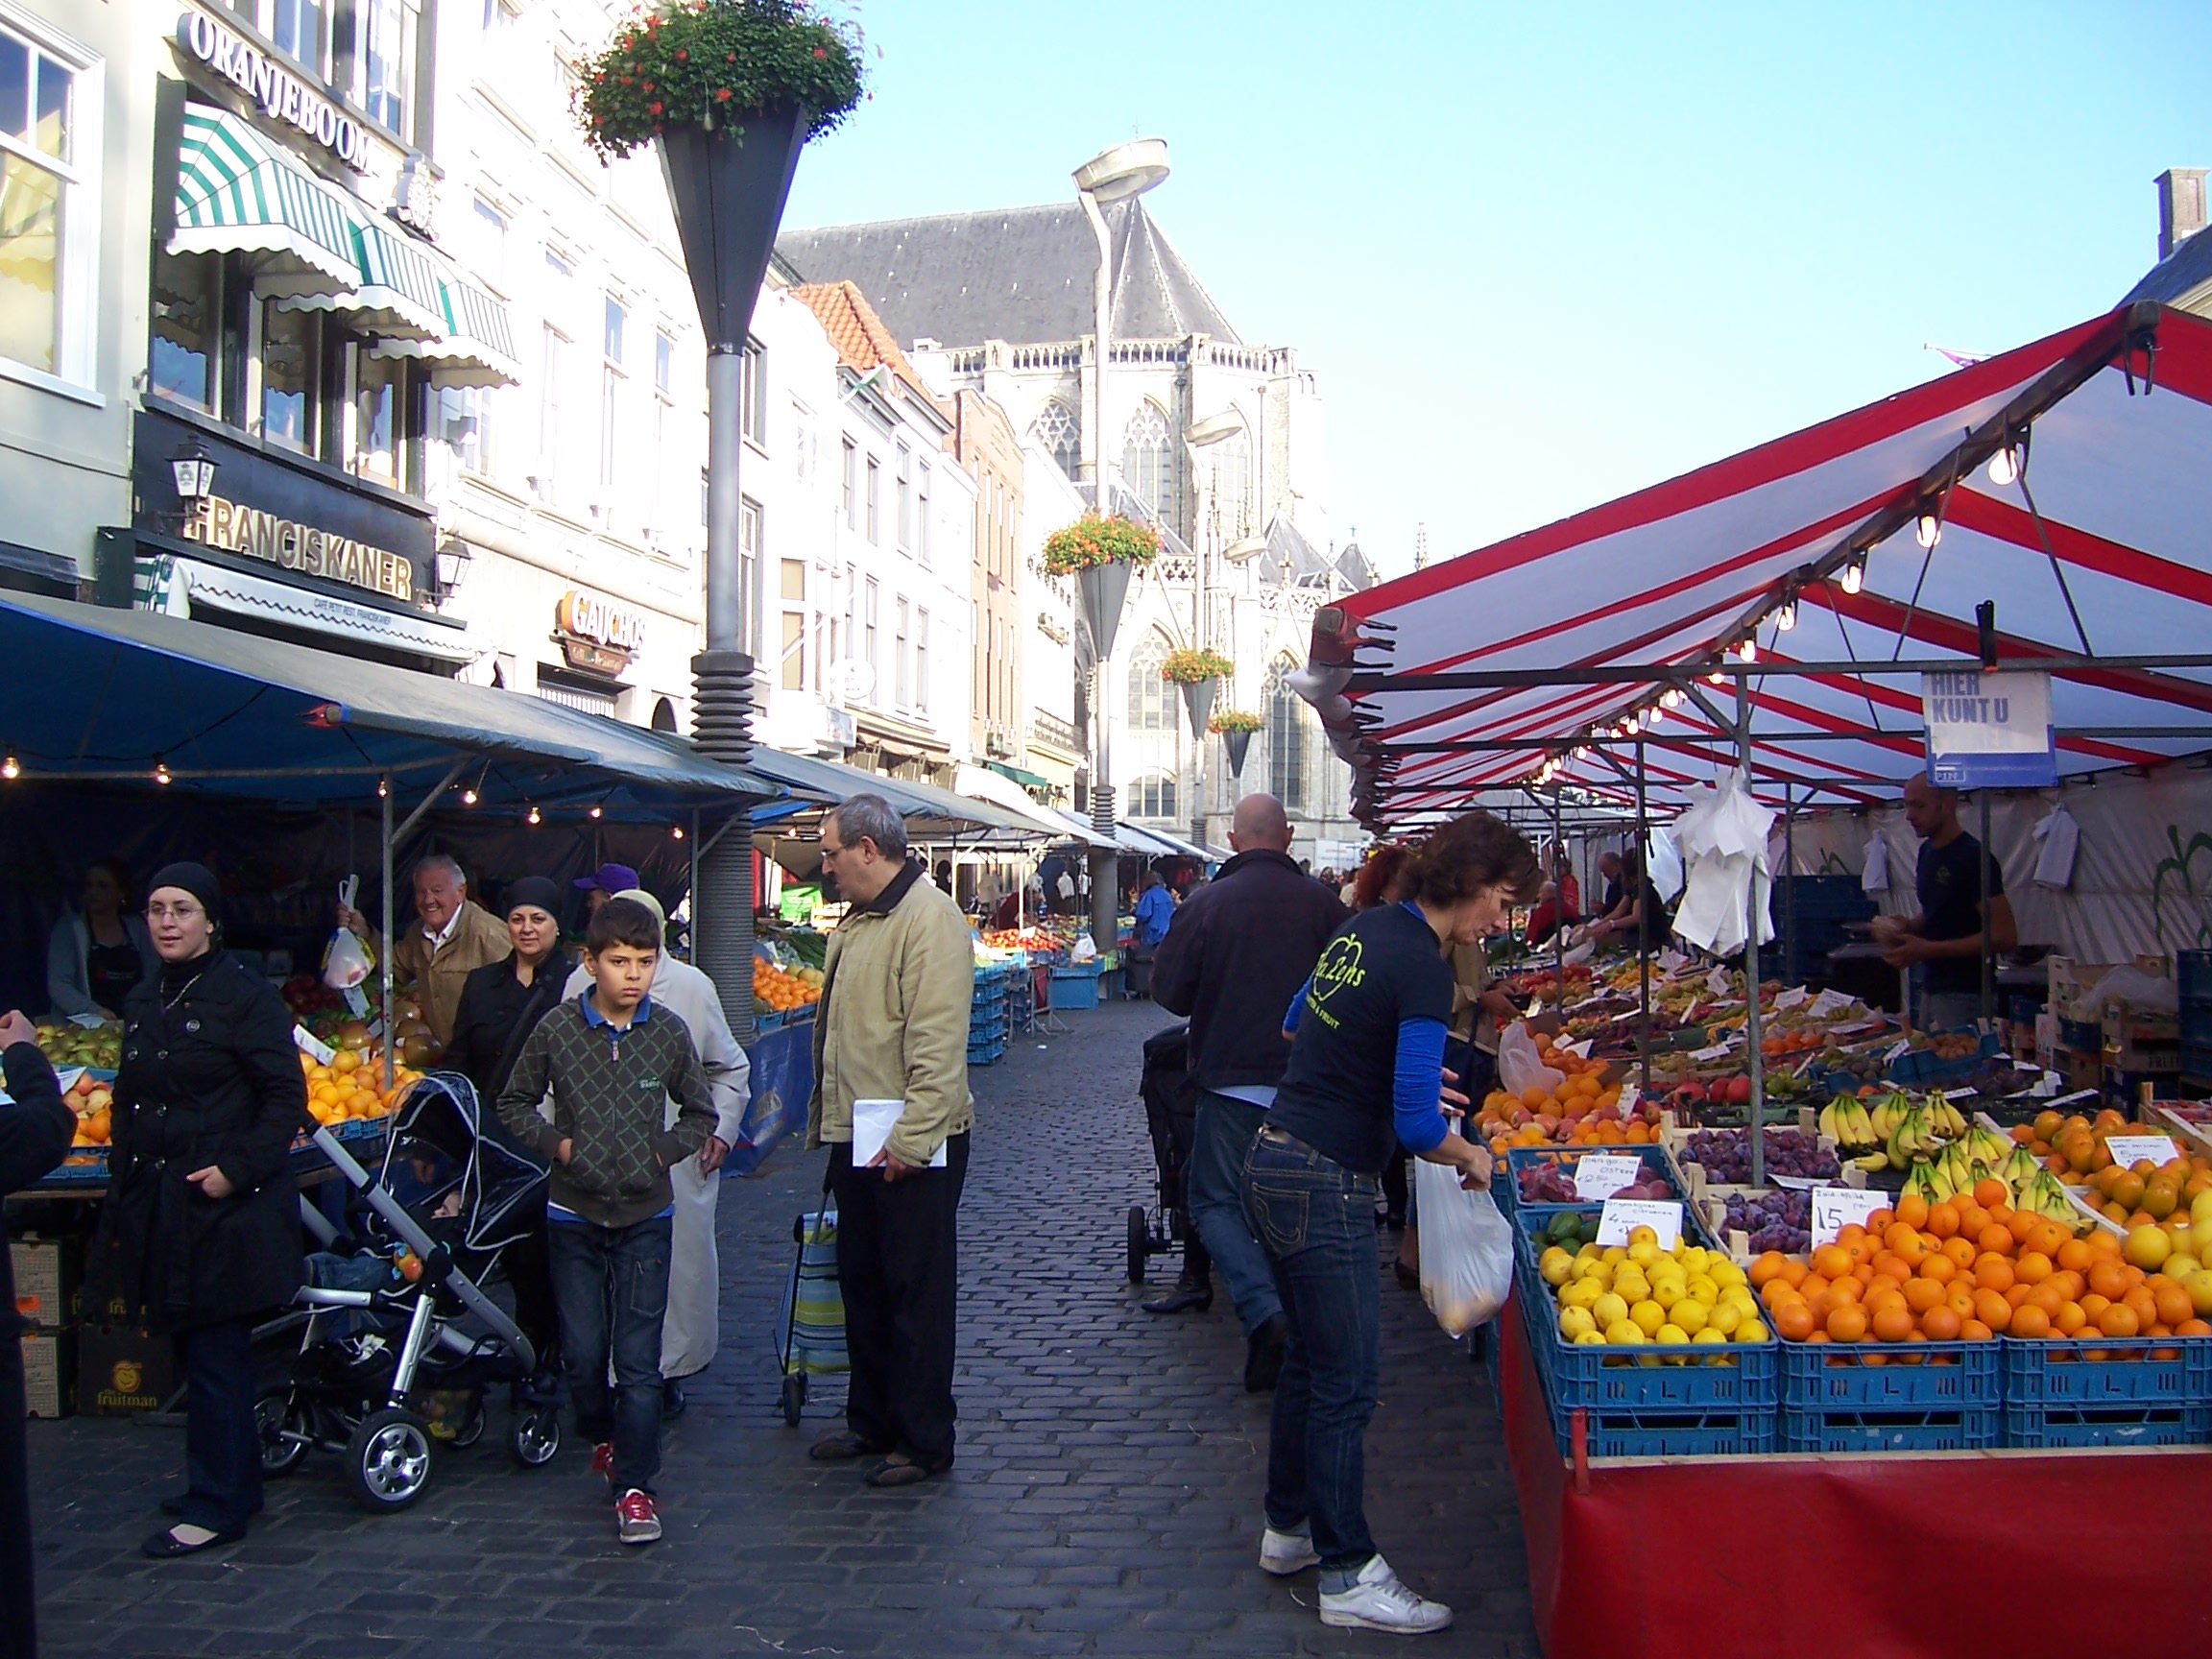
Market in city of BredaDespite the alternative movement, the distinction between conventional and alternative is not so clear (Kirwan et al, publication forthcoming; Sonnino & Marsden, 2006). Therefore it is important to research aspects of both alternative as conventional food supply chains (FSCs). The main part of the food system is conventional, which means it is important to also look at the potential for sustainable possibilities within conventional FSC. AFNs like farmers’ markets have been researched often, however there is hardly any research done on the role of local food and short food supply chains (SFSCs) within supermarkets and traditional markets as part of the conventional FSC. Especially the traditional markets are forgotten. In addition, the traditional markets, as an important source of fresh food in the Netherlands, are under pressure. Many Dutch organizations are looking for solutions for the future of the markets, as they have much difficulty by keeping up with the changes in society. A focus on sustainable food could mean a solution. Supermarkets are powerful organizations which already are trying to win the consumer preferences by selling organic and labeled typical products. While there has been done nothing to look at the potential of the fresh markets as a tool for sustainable development, because the food supply chain of the traditional markets is hardly known. This is why it is important to get insight into the situation of traditional markets.

The goal of this research is to make clear how the food supply chain of four traditional Dutch markets look like and to research the potential of the fresh markets as a part of a local and regional food network. The main research question is: How does the food chain of the traditional fresh markets of the four biggest cities of Brabant look like and in how far is there potential for a larger regional embeddedness?

The share of regional food in the FSC of the fresh markets is larger than expected, namely 13 of the 27 interviewees in fruits and vegetables has a part of their products from their own garden or directly from a farmer. When one also counts the part of the clock auction, then this is 18 of the 27 interviewees. But still the biggest share comes from the wholesalers (59% of the total), so products that come from everywhere. The share of regional food in fruits and vegetables is very differently per city. Cheese is not specifically regional bought. However there is a growing share of organic cheese at the markets. The poulterers sell Dutch chicken, that come from intensive animal husbandry, and is directly bought from the slaughterhouses to be processed by themselves. They also have a growing share of organic meat, but it is still very small. In the hunting-season they also sell game, which comes from local hunters. The fish is mainly bought at wholesalers. Most of the market traders in fish do not pay attention to the MSC-label, but some of them do pay attention to the mating season of the fish, to maintain sustainable development.
The FSCs of the fresh markets of Brabant are not completely conventional and not completely alternative. This research also shows that the distinction is not so clear. The fresh markets have alternative aspects like local products, regional products, important social relations and little waste of food. These aspects however, are not visible to consumers and other parties, because market traders are not aware of it. The alternative aspects are mainly enhanced due to consumers preferences, quality preferences and the underlying traditions of the way of working of the market traders. Also trust plays an important role.

The fresh markets are embedded, especially in socially and cultural aspects, but also in territorial and ecological embeddedness. The fresh markets offer much potential for the enhancement of the embeddedness, but this is not visible in the present discussion on the regionalization of food supply chains. Click here for the thesis in Dutch

De reguliere versmarkten in Nederland; vergeet ze niet!

Door Cleo van Rijk

Markt Breda

Mijn afstudeeronderzoek naar de voedselketen van de Brabantse versmarkten is ontstaan door de vraag of het niet mogelijk is om de bestaande versmarkten te verduurzamen, in plaats van bijvoorbeeld overal boerenmarkten op te zetten. De reguliere versmarkten Nederland zijn nauwelijks onderzocht waardoor het potentieel ervan ook niet bekend is. Daarom heb ik de versmarkten onderzocht van de vier grootste Brabantse steden: ’s-Hertogenbosch, Breda, Tilburg en Eindhoven. Dit heeft tot zeer verrassende resultaten geleid.

Ondanks de tegenbeweging van alternatief is de scheiding tussen conventioneel en alternatief in de werkelijkheid niet zo zwart en wit (Sonnino & Marsden, 2006). Daarom is het van belang om naar specifieke aspecten te kijken binnen beide systemen. Het overgrote deel van het voedselsysteem is conventioneel en daarom is het interessant om ook naar het potentieel hiervan te kijken. Alternatieve voedselnetwerken zijn veel onderzocht, maar er is echter weinig onderzoek gedaan naar lokaal voedsel en korte ketens binnen supermarkten en versmarkten als onderdeel van het conventionele voedselsysteem. Vooral versmarkten wordt grotendeels vergeten. Daarnaast staat de versmarkt, als belangrijke bron van vers voedsel in Nederland, onder druk. Markten hebben het de laatste jaren in heel het land moeilijker gekregen, waarop er nu steeds meer naar oplossingen wordt gezocht. Een focus op duurzaam voedsel kan mogelijk een uitkomst bieden. Supermarktketens zijn machtige organisaties die al sterk bezig zijn om de consument voor zich te winnen doormiddel van biologische en streekproducten. Bij versmarkten is er nog weinig veranderd en ook weinig bekend over deze voedselketen, terwijl er in vrijwel elke stad en dorp een markt is. Door gebrek aan inzicht wordt er niets gedaan om de versmarkt in te zetten als mogelijke vehikel voor duurzame ontwikkeling. Daarom is het belangrijk om inzicht te krijgen in de situatie van conventionele versmarkten.

De hoofdvraag van dit onderzoek is: Hoe ziet de voedselketen van de reguliere versmarkten van de vier grootste Brabantse steden eruit en in hoeverre is er potentieel voor een grotere regionale verankering?

Het aandeel regionaal voedsel is groter dan verwacht, namelijk 13 van de 27 geïnterviewde kooplieden in AGF (groente & fruit) haalt een gedeelte van hun producten uit eigen tuin en/of direct van een boer. Als men de veiling meetelt dan is dit 18 van de 27 AGF-kooplieden. Maar het grootste deel van de producten (59% van het totaal) komt van groothandels, producten die overal vandaan komen. Het aandeel regionaal voedsel in AGF is per stad zeer verschillend. Kaas wordt niet specifiek regionaal ingekocht. Wel wordt er een groeiend aandeel in biologische kaas ingekocht. Poeliers verkopen Nederlandse kip van de gangbare vleeskuikenhouderijen en wordt direct van de slachterij ingekocht waarna ze het zelf verwerken. Men heeft een groeiend aandeel biologisch vlees in het assortiment en in het jachtseizoen wordt wild verkocht, welke direct van lokale jagers afkomt. De vis wordt veelal bij groothandels ingekocht. Hierbij wordt niet veel aandacht besteed aan het MSC-label, maar let men vaak wel op de paringsseizoenen van vissen, voor duurzame ontwikkeling.

De voedselketen van de Brabantse versmarkten bevat zowel conventionele en alternatieve aspecten. De stelling van Marsden en Sonnino (2006) dat er geen scherpe scheiding is tussen ‘alternatief’ en ‘gangbaar’ wordt hiermee bevestigt. De versmarkten zijn niet geheel conventioneel en niet geheel alternatief. De alternatieve aspecten zijn echter niet goed zichtbaar, omdat de kooplieden er niet bewust mee bezig zijn. De versmarkt heeft alternatieve aspecten zoals lokale producten, regionale producten, sterke sociale verbindingen en weinig voedselverspilling. De alternatieve aspecten worden vooral bevorderd door klantenvraag, kwaliteitseisen van de kooplieden zelf en onderliggende tradities bij de marktkooplieden. Ook vertrouwen speelt hierin een grote rol.

De markt is verankerd, vooral in sociaal en cultureel opzicht, maar ook in territoriale en ecologische verankering. De markt biedt veel potentie voor het vergroten van de verankering, maar is onzichtbaar in de huidige discussie over de regionalisering en verduurzaming van voedselsystemen.

Voor meer informatie: klik hier voor het volledige rapport.

Multifunctionele landbouw is een sector met toekomst

Ondernemen in de multifunctionele landbouw is niet voor stoppers, maar biedt juist toekomstperspectief. Het vervlechten van nieuwe activiteiten (zoals zorg, recreatie, educatie, huisverkoop etc.) met de agrarische productie zorgt voor een aanzienlijke bijdrage aan het gezinsinkomen en verdere ontwikkeling van de agrarische activiteiten. Dit blijkt uit het onderzoek ‘Dynamiek en Robuustheid van Multifunctionele Landbouw’ dat in opdracht van het ministerie van EL&I werd uitgevoerd door de leerstoelgroep Rurale Sociologie van Wageningen University. Het onderzoek is gebaseerd op diepte-interviews met 120 multifunctionele landbouwondernemers. De ondernemers komen uit het Brabantse Groene Woud, Flevoland, Laag-Holland (Noord-Holland), het Zeeuwse Walcheren/Zuid-Beveland, De Drentse Wolden en de Noordelijke Friese Wouden.

Robuustheid

Uit de interviews blijkt ten eerste dat bij de komst van nieuwe activiteiten vooral positieve drijfveren een rol spelen, meer dan een te laag inkomen. Betrokken boeren en boerinnen hebben vaak behoefte aan meer contact met burgers, consumenten en de maatschappij. Ten tweede blijkt dat op de onderzochte bedrijven gemiddeld bijna drie verschillende activiteiten voorkomen, in verschillende combinaties.

De verschillende combinaties van multifunctionele activiteiten op de onderzochte bedrijven zorgen voor een gemiddelde omzet van 195.000 euro (aanvullend op de agrarische omzet). De activiteiten leveren – met gemiddeld 40 procent – een aanzienlijke bijdrage aan het totale gezinsinkomen. Sinds de start van de nieuwe activiteiten is er bovendien op het overgrote deel van de bedrijven sprake van een positieve wisselwerking met verdere agrarische ontwikkeling. Agrarische omzet, grondgebruik en arbeidsinzet blijft behouden of groeit.

De robuustheid van multifunctionele bedrijvigheid blijkt verder ook uit de positieve beoordeling van het totale bedrijfsinkomen door boeren, groeiende omzetten en inkomensbetekenis en de geleidelijke uitbreiding van het aantal nieuwe bedrijfsactiviteiten in de tijd. Ook de totale arbeidsinzet op betrokken bedrijven neemt geleidelijk aan toe. “Multifunctionele landbouw is dus niet alleen van betekenis voor betrokken bedrijven, maar zeker ook voor de plattelandseconomie als geheel”, aldus projectleider Han Wiskerke.

Verschillen

Het onderzoek laat zien dat er grote verschillen bestaan in dynamiek en robuustheid van onderzochte bedrijven. Dit wordt enerzijds verklaard door regionale verschillen, zoals de aanwezigheid van sterke samenwerkingsverbanden als belangrijke succesfactor. Daarnaast maken ook meer bedrijfsgebonden factoren verschil. Te denken valt aan verschillen in bedrijfsstrategie zoals de mate van investeren, het wel of niet werken met personeel en in hoeverre er wisselwerking plaatsvindt tussen de verschillende bedrijfsactiviteiten.

Taskforce

De Taskforce Multifunctionele Landbouw zet zich namens het ministerie van EL&I in voor de verdere ontwikkeling van zorglandbouw, streekproducten, recreatie, agrarische kinderopvang en educatie en natuurbeheer. Kenniscoördinator Arjan Monteny: ,,Het onderzoek toont aan dat multifunctionele landbouw een stevig fundament heeft: ondernemers durven erin te investeren en behalen rendement uit de nieuwe bedrijfsactiviteiten. Het is mooi dat dit vaak gepaard gaat met verdere ontwikkeling van de agrarische activiteiten. Multifunctionele landbouw is daarmee onlosmakelijk verbonden met de agrarische productie. Het is duidelijk geen exit-strategie.”

Rapport

Het onderzoeksrapport is te downloaden via de website van het onderzoeksproject.

Bron: deze blog is een overname van een gezamenlijk persbericht van de leerstoelgroep Rurale Sociologie en de Taskforce Multifunctionele Landbouw

Rural regional learning in ‘Upper Lusatia’ (Oberlausitz), Germany

Following my visit to Alytus County, Lithuania in October, I travelled to Leipzig, Germany to visit our DERREG project partners Michael Kriszan, Robert Nadler and Joachim Burdack (Leibniz Institute for Regional Geography) in their case study area ’Upper Lusatia’. In this blog, Michael, Robert, Joachim and I would like to share some of our experiences.

We first discovered that the case study regions Westerkwartier and Upper Lusatia are very different in their geographical and demographical characteristics. The LEADER region Westerkwartier in Groningen province comprises four municipalities on an area of 374km² and has a population density of 173.4 inhabitants/km² (as of 2007). In 2006, its GDP per capita was estimated at 55,400 Euro and the area has recently witnessed a population increase due to its popularity amongst young families who work in the city of Groningen and value the countryside as their residential area. The Southern part of the Westerkwartier is thus characterized by a high population density and a number of conflicting interests regarding the use of the countryside while the North of the Westerkwartier is primarily used for agriculture.

Upper Lusatia consists of the two Saxon districts Landkreis Görlitz and Landkreis Bautzen that have only been established in 2008 in the process of a reform of the administration units in Saxony. The case study region has an area of about 4,500 km² and has a population density of 135 inhabitants/km². It comprises 122 municipalities- of which 30 are urban centers- and had a GDP per capita of 18,329 Euro (district Görlitz) respectively 19,396 (district Bautzen) in the year 2007 . The region is divided into ten rural development areas, six ILE regions and four LEADER regions. In contrast to the Westerkwartier, the population of Upper Lusatia is shrinking rapidly. Young inhabitants are leaving the area due to a lack of employment opportunities, leaving the elder people behind. Rural development in this region is therefore not only affected by an aging population but also by a shrinking human capital available for development purposes. Through the reform of administrative units altogether four previously distinct districts (Landkreise) and two cities (kreisfreie Städte) have been incorporated into the two “new” districts of Görlitz and Bautzen. The previous Landkreise, however, are very distinct in their physical appearance. The former district Niederschlesien-Oberlausitz for example is characterized by a low population density and shaped through past and present coal mining activities while the hilly district Löbau-Zittau is recognized as a touristic area and winter sport resort. Due to the lack of a common history and the physical distinctiveness, there is no regional identity of the population within both districts.

To evaluate the support and facilitation available for learning and innovation within local grassroots development initiatives in Upper Lusatia, Robert, Michael and Joachim organized a workshop for regional stakeholders.

Workshop in Upper Lusatia, Germany

Continue reading →

FAQs for PUREFOOD vacancies

We have received a high number of inquiries with regard to our 12 PUREFOOD vacancies. It is good to see there is so much interest in these topics!
Most reactions were inquiries about similar issues. Therefore, we have prepared a list of FAQs for the PUREFOOD vacancies. Please have a look at this list of FAQs before sending us an e-mail!